Workers who earned overtime in 2026 should find claiming the new federal overtime tax break simpler than those filing for 2025, after the IRS clarified how the benefit will be reported and who qualifies. The agency updated its frequently asked questions, and employers are now required to put eligible amounts on employee tax forms, reducing the paperwork burden on taxpayers.
What changed for 2026
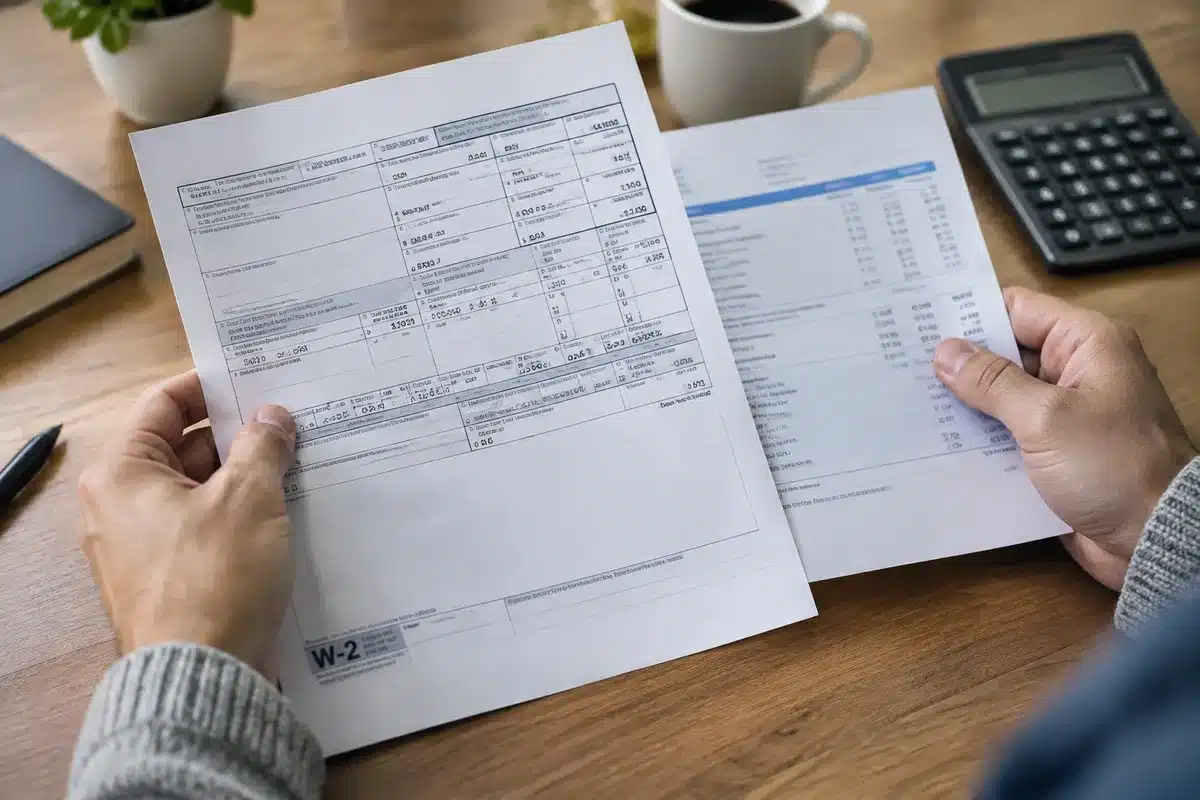
The IRS issued expanded guidance to clear up confusion that emerged when taxpayers first used the so‑called “no tax on overtime” deduction for 2025 returns. Under the revised rules, employers must report the eligible overtime amount on employees’ W‑2 forms in box 12 using code TT for the 2026 tax year. That shifts responsibility for calculating and disclosing the figure from many workers to their employers.
Tax professionals say the reporting change should simplify filings. When the deduction debuted, the Treasury and IRS temporarily waived employer reporting because payroll systems and tax forms were not yet updated, forcing many workers to estimate their eligible overtime from pay stubs.
How the deduction actually works
The tax break applies only to the overtime “premium” — the extra half of an employee’s rate when paid at 1.5 times their regular wage, as required by the Fair Labor Standards Act (FLSA). For example, if a worker’s normal pay is $40 per hour and overtime pays $60 per hour, the deductible amount is $20 per hour: the premium above the regular rate, not the full overtime wage.
Two important limits apply:
- Maximum deductible amount: up to $12,500 for single filers and $25,000 for married couples filing jointly.
- Phaseout thresholds: the deduction begins to phase out at $150,000 of income for single filers and $300,000 for joint filers.
State laws or union contracts that require higher overtime pay do not expand the federal deduction. The IRS guidance says only the portion of overtime mandated by federal rules — generally the half‑time premium under the FLSA — qualifies for the tax break. And while independent contractors might sometimes receive a 1099 that includes extra pay, the IRS considers that situation uncommon.
How many taxpayers used it in 2025?
The Treasury Department reported that more than 29 million taxpayers claimed the overtime deduction when filing 2025 returns, with an average benefit just above $3,100. Most claimants were middle‑income: about three‑quarters had adjusted gross income under $100,000, and 96% reported incomes under $200,000.
Because employers were not required to report the eligible overtime amount for 2025, many filers and preparers reconstructed the figure from year‑end pay statements. Tax professionals warn those estimates carried risks: if an employer later provides a different number on a corrected W‑2, taxpayers cannot simply substitute their own calculation on a return.
Practical steps for 2026 filers
Even though your employer should now report the deduction amount, experts advise verifying the figure against your payroll records.
- When you get your 2026 W‑2, check box 12 for code TT and confirm the amount matches your records.
- Bring year‑end pay stubs to your tax preparer — they can help reconcile the W‑2 entry and spot discrepancies.
- If the W‑2 shows an error, ask your employer for a corrected form (a W‑2c) before filing.
As one tax adviser put it, employees should not assume the employer’s number is infallible, but they also cannot unilaterally change the reported amount on their return without documentation. Requesting a corrected W‑2 is the proper remedy when a mismatch appears.
Quick reference: who qualifies and what’s reported
| Topic | Details |
|---|---|
| Eligible pay | Overtime premium (the extra 0.5× under FLSA), not total overtime wages |
| Reporting | Employers must report eligible amount on W‑2, box 12, code TT (2026 onward) |
| Limits | Up to $12,500 (single) / $25,000 (joint) |
| Phaseout | Begins at $150,000 (single), $300,000 (joint) |
| 2025 filing note | Employers were not required to report; taxpayers often calculated eligible amounts themselves |
The IRS FAQs provide the official details; as payroll systems and employer reporting settle into the new requirements, the practical effect should be fewer calculation headaches for individual filers. Still, workers should review their W‑2s closely and be prepared to seek corrections if the reported overtime premium appears incorrect.
Similar Posts
- Trump overtime tax break prompts millions to claim deduction: filing errors likely
- Tax refunds up 11%: IRS data shows bigger checks for taxpayers
- 2026 IRS Brackets Revealed: Inflation Drives Major Standard Deduction Increase!
- IRS refunds jump 10.6%: latest filings show bigger payouts for taxpayers
- Tax refunds rise 10.6%: early filings point to bigger checks for many

Jordan Keller specializes in analyzing the US financial markets. With concrete recommendations, he helps you secure and boost your investments by providing strategies that adapt to market fluctuations.