President Trump used an Oval Office event Wednesday to push families to accept newly created government investment accounts for children, after federal officials completed an automatic enrollment that opened nearly 70 million accounts. The move — paired with last week’s Treasury and IRS guidance allowing stock donations to those accounts — could deliver immediate money to some families while reshaping how philanthropists support child savings programs.
What changed and why it matters now
Federal officials say more than 60 million accounts were added this month as part of an automatic-enrollment effort that ultimately created nearly 70 million Trump Accounts. The Treasury has also launched a short-term pilot that places a one-time, $1,000 seed deposit into accounts for children born from 2025 through 2028.
Last week’s temporary regulations permit individual stock gifts into these accounts, a departure from earlier rules that required diversified index funds. The combination of mass enrollment and new donation rules has already prompted large philanthropic commitments and could change how families and donors interact with the program.
Key facts at a glance
- Accounts created: Nearly 70 million children now have an account in their name through automatic enrollment.
- Pilot seed deposit: One-time $1,000 contribution for eligible children born 2025–2028.
- Donations allowed: Temporary IRS/Treasury guidance allows individual-stock donations that generally must be held for five years before sale.
- Reported funds: The administration reported more than $4.5 billion deposited so far from seed funds, private contributions and philanthropic gifts.
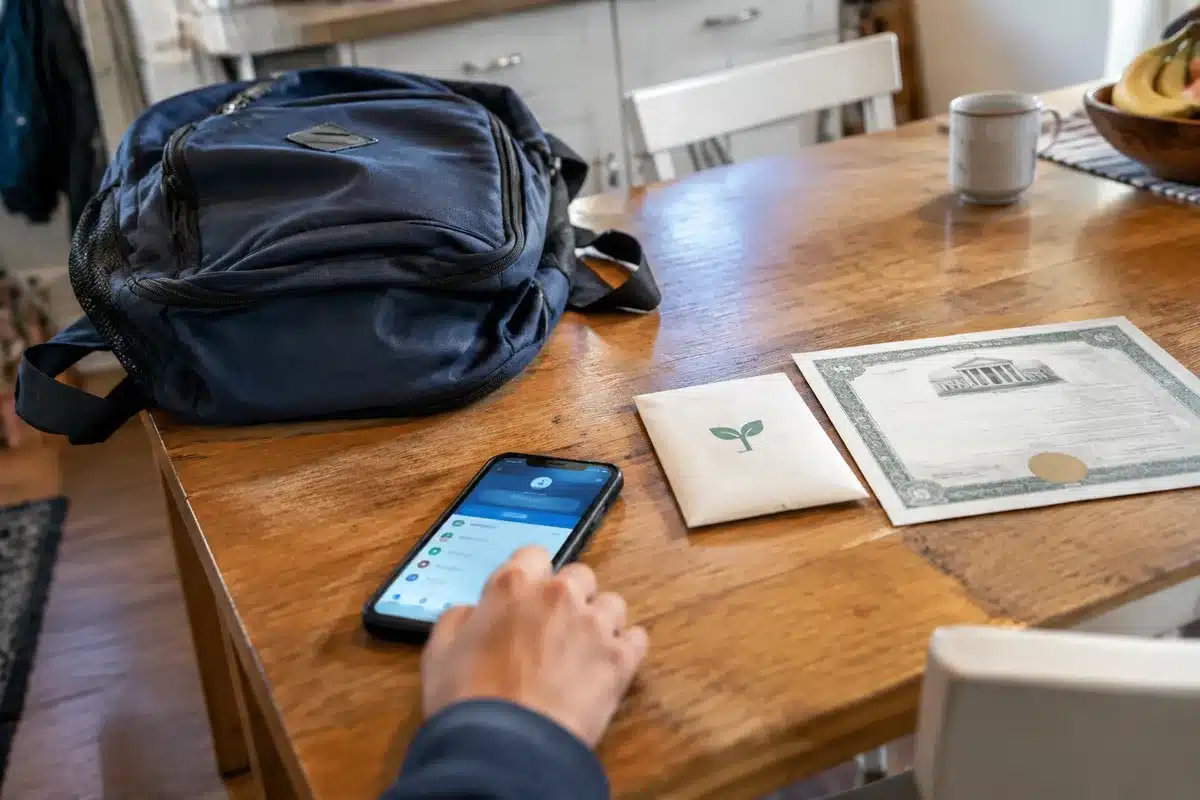
- How to claim: Parents or guardians must verify identity and relationship through the Trump Accounts app to accept and manage an account.
How the new stock-donation rules work
The Treasury’s temporary guidance lets donors transfer individual shares into accounts rather than requiring cash or indexed fund investments. Donated stock is typically restricted from sale for five years, a condition meant to limit rapid flips and preserve long-term savings.
Financial advisers say the change increases the appeal for wealthy donors who would otherwise face capital-gains taxes if they sold shares before giving cash. That tax treatment can make large gifts from founders and early shareholders more tax-efficient.
But there’s a trade-off: accepting individual stocks can concentrate a child’s portfolio in a single company, exposing account holders to greater volatility compared with broadly diversified funds.
Major donors and public commitments
High-profile attendees at Wednesday’s White House event included tech and finance executives who have already pledged sizable support to child savings efforts. One notable family committed multibillion-dollar grants to target children in lower- and middle-income ZIP codes, while other investors said they plan to seed accounts in specific states.
Administration officials said a roster of philanthropic backers is growing and ranges from modest contributors to donors making nine-figure commitments. Those offers, if realized, could channel substantial private capital into the program.
How families enroll and claim the seed deposit
Every child under 18 with a Social Security number was included in the automatic enrollment. To take control of an account and claim the pilot seed deposit if eligible, parents or guardians must:
- Download the Trump Accounts app
- Verify identity and relationship to the child
- Review the account details and accept terms
A White House spokeswoman described the seed deposit as an important starter contribution for families that qualify, while noting that automatic enrollment was intended to expand access.
How Trump Accounts compare with other options
The accounts — also referred to in regulatory filings as 530A accounts — are a new, tax-deferred vehicle open to U.S. children under 18. They are not identical to existing college-savings or custodial accounts and may not suit every financial goal.
For families focused specifically on education costs, a 529 plan still offers tax-free withdrawals for qualified school expenses. Custodial brokerage accounts remain an option for parents who want direct control over investments but carry different tax rules and potential consequences.
Taxes and planning considerations
Custodial accounts are subject to annual taxation and the so-called “kiddie tax.” For 2026, the thresholds are:
- $0–$1,350 of investment income: tax-free
- $1,350–$2,700: taxed at the child’s rate
- Over $2,700: taxed at the parents’ rate
Some advisers describe strategies — such as selling gains up to the tax-free threshold and repurchasing the same holdings to reset the cost basis — that can be used in custodial accounts to manage future capital-gains exposure. Those techniques may not apply in the same way to Trump Accounts, especially when stock-donation holding rules are in effect.
Families weighing options should consider investment goals, time horizon and tolerance for concentrated risk. Financial professionals note that while donated stock can increase near-term funding, it can also tie a child’s savings to the fortunes of a single company.
Political and timing context
The rollout arrives as midterm elections approach and lawmakers from both parties weigh the program’s costs and benefits. Changes to donation rules and the visible participation of major donors have injected fresh public attention — and political scrutiny — into how the accounts will operate long term.
For parents and guardians, the immediate takeaway is practical: check whether your child’s account was created, verify eligibility for the $1,000 pilot deposit, and consider how these accounts fit into broader savings and tax plans.
Similar Posts
- IRS confirms Trump account donations won’t require annual gift tax reporting
- Dell Foundation $250 aid for Trump account holders launches Monday
- Trump accounts may start taking stock gifts, reports say
- Trump signups surpass 6 million: millions more kids eligible to join
- Trump account signups top 7 million: campaign hails unprecedented government launch

Jordan Keller specializes in analyzing the US financial markets. With concrete recommendations, he helps you secure and boost your investments by providing strategies that adapt to market fluctuations.